DETROIT, United States — General Motors delivered stronger-than-expected third-quarter results on October 20, 2026, with revenue reaching $50.02 billion and adjusted earnings climbing more than 32%, but its shares dropped sharply as investors focused on rising costs and uncertainty surrounding the automaker’s 2027 outlook.
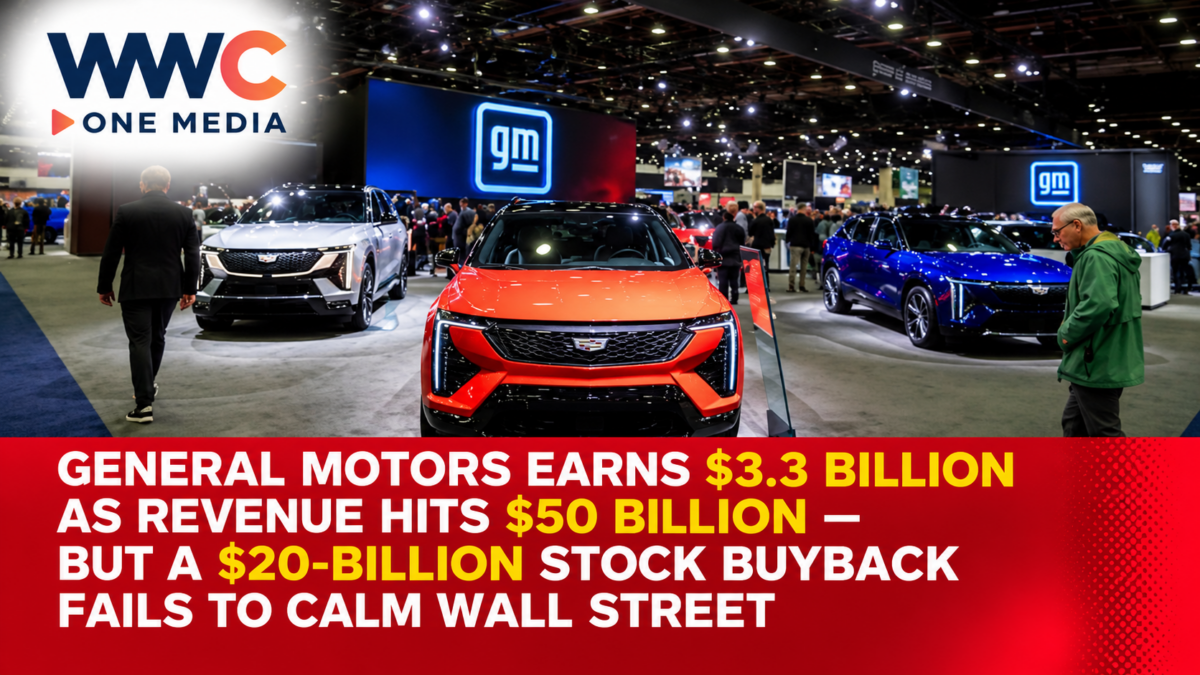
The Detroit-based manufacturer of Chevrolet, GMC, Cadillac and Buick vehicles reported net income attributable to shareholders of approximately $3.34 billion for the quarter ended September 30.
Adjusted earnings reached $3.70 per share, above analyst expectations of approximately $3.63 to $3.65 per share.
GM’s adjusted operating profit increased nearly 22% to $4.11 billion, driven primarily by its highly profitable North American pickup truck business.
The company also approved a new $20-billion multiyear share repurchase program, one of the most significant capital-return announcements in the automotive industry.
But despite strong earnings and billions of dollars earmarked for shareholders, GM’s stock fell more than 5% during trading on October 20.
The reason: investors were increasingly concerned that rising commodity costs, expensive logistics, production changes and intensifying competition could undermine future profits.
The biggest question is whether GM can sustain its record of strong cash generation while absorbing billions in additional expenses—or whether 2027 will become a far more difficult year for America’s automotive giant.
GM Revenue Reaches $50 Billion in Third Quarter
General Motors reported revenue of $50.015 billion for the third quarter of 2026.
That represents an increase of 2.9% from $48.591 billion a year earlier.
The automaker’s performance exceeded the approximately $48.7 billion in revenue expected by analysts.
The increase came despite challenges in vehicle demand and changes in its product mix.
Revenue growth alone, however, does not fully explain GM’s financial performance.
The company generated substantially higher profit margins as its North American operations benefited from sales of larger and more profitable vehicles.
The results demonstrate that vehicle pricing, production efficiency and product selection can influence earnings even when overall market demand is uneven.
But the durability of those margins remains a critical concern as vehicle production and operating costs change.
Net Income Jumps to $3.34 Billion
GM reported approximately $3.335 billion in net income attributable to stockholders.
That was more than double the $1.327 billion recorded during the same period in 2025.
Reported diluted earnings per share reached $3.73, compared with $1.35 a year earlier.
However, investors should distinguish reported earnings from adjusted financial measures.
The company also presented adjusted diluted earnings of $3.70 per share.
The adjusted figure excludes specified items under GM’s reporting methodology and is commonly used in comparisons with Wall Street earnings expectations.
The stronger profit performance was supported by operating results, but changes in special items also affect the year-on-year comparison of reported net income.
That is why the company’s approximately 22% increase in adjusted operating profit offers a useful additional measure of its underlying business performance.
Adjusted Operating Profit Surges 22%
GM’s earnings before interest and taxes, adjusted for certain items, reached $4.106 billion.
That compares with $3.376 billion in the third quarter of 2025.
The increase was 21.6%, rounded to 22%.
Its adjusted EBIT margin improved from 6.9% to 8.2%.
This means GM generated a greater level of adjusted operating profit for each dollar of revenue.
The improvement was particularly significant because revenue grew at a much slower pace.
A more favorable mix of high-margin vehicles helped support profitability.
But the company will need to protect that advantage against changes in vehicle demand and material costs.
North American Trucks Deliver the Biggest Earnings Boost
GM’s North American business was the strongest contributor to the quarter.
Adjusted operating profit in the region climbed to approximately $3.59 billion from $2.51 billion a year earlier.
That represents an increase of more than 43%.
The North American adjusted operating margin improved from 6.2% to 8.7%.
Large pickup trucks played an important role.
Vehicles such as the Chevrolet Silverado and GMC Sierra remain major profit generators because customers often purchase higher-priced configurations and optional features.
Strong demand for these models helped GM offset weakness in other areas.
However, the strategy also creates exposure to consumer spending patterns.
If high fuel prices or borrowing costs shift customers toward smaller and more efficient vehicles, GM’s dependence on profitable trucks could become a vulnerability.
$20-Billion Share Buyback Signals Confidence
GM announced that its board had approved a new multiyear share repurchase authorization worth $20 billion.
The move follows completion of a separate $6-billion buyback program announced in January 2026.
Through repurchases, a company buys back its own shares from investors.
This can reduce the number of shares outstanding and potentially increase earnings per share, assuming other conditions remain unchanged.
GM had approximately 849 million shares outstanding at the end of September 2026.
That compares with 904 million at the end of 2025 and about 1.2 billion at the end of 2023.
The reduction reflects the company’s continuing commitment to returning capital to shareholders.
But the new $20-billion authorization is not an announcement that the entire amount has already been spent.
The program has no fixed expiration date and can be suspended or discontinued.
Actual purchases will depend on management decisions and market conditions.
GM Maintains Quarterly Dividend
Alongside the buyback, General Motors declared a quarterly cash dividend of $0.18 per common share.
The dividend is scheduled for payment on December 17, 2026.
Shareholders must be on record as of the close of trading on December 4 to qualify under the announcement.
The payment reinforces GM’s shareholder-return strategy.
However, a declared dividend and a share repurchase authorization are different capital-return mechanisms.
Dividends provide a specified cash payment to eligible shareholders.
Buybacks depend on actual share purchases and do not guarantee that the stock price will increase.
The company’s ability to sustain shareholder distributions will depend on future earnings, cash flow and investment requirements.
Why GM Stock Fell Despite Strong Results
The market reaction was one of the most notable elements of GM’s earnings announcement.
The company’s adjusted earnings beat analyst expectations.
Its revenue also exceeded forecasts.
And management announced another major shareholder-return program.
Nevertheless, the shares declined during October 20 trading.
Reuters reported an approximately 5% decline during the session, while other market coverage described a deeper selloff later in trading.
The negative reaction reflected disappointment over GM’s revised annual earnings outlook and concerns about 2027.
The company narrowed its forecast ranges but did not deliver the stronger profit improvement some investors had hoped for.
Analysts also questioned whether GM could maintain its favorable mix of profitable pickup sales while facing cost inflation and new production adjustments.
For Wall Street, a strong quarter was not enough to eliminate doubts about future earnings.
GM Narrows Full-Year Profit Guidance
General Motors revised its full-year 2026 adjusted operating profit forecast to between $14.5 billion and $15.5 billion.
The previous guidance ranged from $14 billion to $16 billion.
The new range is narrower but has the same $15-billion midpoint.
That distinction helps explain the disappointment.
GM improved the certainty of its expected result without raising the midpoint of its core operating-profit forecast.
The company also revised adjusted earnings per share guidance to $12.75–$13.75 from the previous $12–$14 range.
Its updated outlook for net income attributable to shareholders is $8.9 billion to $9.5 billion.
The figures remain forecasts, not completed full-year results.
They also remain subject to economic conditions, production schedules and other business risks.
Free Cash Flow Outlook Improves
Not every part of GM’s outlook disappointed investors.
The company increased its 2026 adjusted automotive free cash flow forecast to between $11.5 billion and $12.5 billion.
Its previous forecast was $9.5 billion to $11.5 billion.
In the third quarter alone, adjusted automotive free cash flow reached approximately $5.88 billion, up 40% from $4.2 billion a year earlier.
Automotive operating cash flow climbed to approximately $8.05 billion.
These figures are important because cash generation supports capital spending, debt obligations and shareholder returns.
The stronger outlook suggests GM expects its vehicle business to remain capable of generating substantial cash.
However, adjusted automotive free cash flow is not identical to consolidated net income or the total cash available without restrictions.
It is a specific non-GAAP performance measure defined and reconciled by the company.
Rising Commodity Costs Threaten 2027
The most serious forward-looking warning concerns costs.
GM expects commodity inflation, logistics and related pressures to weigh on its business.
During its earnings discussions, management indicated that increased costs could reach approximately $2 billion in 2026.
Chief Financial Officer Paul Jacobson also warned that, if recently elevated commodity expenses persist, they could create an approximately $2-billion additional headwind in 2027.
These are distinct scenarios and should not automatically be combined into a $4-billion realized loss.
The company identified pressure from materials such as steel and aluminum, alongside transportation and semiconductor-related costs.
Automakers rely on extensive global supply chains, making them sensitive to commodity prices and production disruptions.
If costs rise faster than vehicle prices, profit margins can narrow.
GM must therefore find ways to manage expenses without undermining product quality, manufacturing reliability or customer demand.
Tariffs Add Another Layer of Uncertainty
Trade-related costs remain another challenge.
GM previously forecast gross tariff costs between $2.5 billion and $3.5 billion for 2026.
The company now expects those costs to fall near the lower end of that range.
That is more favorable than experiencing the full upper-end estimate.
But it still represents a significant expense.
Gross tariff exposure is not necessarily the same as the final net impact on profits after mitigation measures.
Automakers can adjust sourcing, production arrangements, pricing and other operations to manage trade costs.
However, such changes can require substantial investment and time.
For a manufacturer operating across multiple countries, uncertainty around tariffs complicates long-term planning.
New Pickup Models May Disrupt Fourth-Quarter Deliveries
GM is preparing redesigned versions of two of its most important vehicles: the Chevrolet Silverado and GMC Sierra.
Model transitions typically require factory retooling and production adjustments.
Management indicated that these activities would reduce full-size pickup deliveries in the fourth quarter.
The company expects approximately 35,000 fewer full-size pickup sales during the period compared with a year earlier, according to market reporting on its production outlook.
This matters because large pickups are among GM’s strongest contributors to operating earnings.
Temporary production interruptions can affect wholesale deliveries and near-term revenue.
But the transitions are also intended to support future product competitiveness.
Investors will therefore be watching whether the redesigned models can sustain customer demand and attractive margins after launch.
Electric-Vehicle Strategy Faces a Reset
GM’s latest results also illustrate a change in the economics of its electric-vehicle strategy.
The company has reduced some EV production and investment commitments as market demand and U.S. policy incentives have changed.
Reuters reported that a more favorable mix of large pickup trucks and fewer EV sales contributed to improved profitability in the quarter.
That does not mean GM has abandoned electric vehicles.
The company continues offering EV products and investing in technology.
But it is attempting to balance long-term electrification goals with the near-term returns available from gasoline-powered trucks and SUVs.
The financial challenge is significant.
Investments in manufacturing, batteries and new platforms require large amounts of capital.
If customer demand develops more slowly than expected, the company may face underutilized capacity and additional restructuring charges.
EV Realignment Charges Have Declined
Special adjustments related to GM’s electric-vehicle strategic realignment were approximately $238 million in the third quarter of 2026, compared with around $1.59 billion in the corresponding quarter a year earlier.
The lower charge helped reduce the impact of exceptional items on current-period results.
But it should not be confused with evidence that every GM electric vehicle has become profitable.
The charges relate to specified strategic adjustments recorded under the company’s accounting.
The profitability of individual models and EV operations involves additional manufacturing, pricing, development and operating factors.
The company continues managing its transition as customer preferences and government policies evolve.
GM Faces Competition From Hybrid Vehicles
GM is also encountering a challenge in the growing hybrid-vehicle market.
Hybrids combine gasoline engines with electric propulsion technology and can offer improved fuel efficiency without requiring drivers to rely exclusively on external charging.
Reuters reported that hybrid vehicles now account for more than 15% of U.S. vehicle sales.
GM has had limited participation in this category compared with some competitors.
Analysts have argued that the lack of a broader hybrid lineup creates a competitive disadvantage, especially if customers want more fuel-efficient vehicles but are not ready to switch completely to electric cars.
Chief Executive Mary Barra told analysts that GM would introduce hybrids, although she did not provide a firm timetable or detailed product announcement during the discussion.
The company will need to decide how quickly it can respond to changing consumer preferences while managing existing investments.
International Operations Remain Under Pressure
GM’s North American strength contrasted with weaker performance elsewhere.
Its international operations generated adjusted EBIT of approximately $28 million, compared with $226 million a year earlier.
That represents a decline of nearly 88%.
GM’s equity income from China also decreased to approximately $32 million from $80 million.
These results demonstrate that global operations are not experiencing the same profitability trends.
Competition, pricing and market conditions differ substantially between countries.
A strong performance in U.S. pickup trucks cannot fully insulate GM from international weakness.
The company has indicated that some markets outside China may remain challenging.
For investors, continued geographic concentration of profit is both an advantage and a risk.
GM Financial Also Reports Lower Earnings
The company’s financial services division experienced weaker results.
GM Financial recorded adjusted earnings before taxes of approximately $668 million, down from $804 million a year earlier.
The unit provides financing services associated with vehicle purchases and leasing.
Its performance can be affected by borrowing costs, credit conditions, vehicle values and consumer financing behavior.
Although GM’s core North American automotive business produced stronger margins, weaker results in financial services reduced some of the overall benefit.
This underscores why an automaker’s financial performance cannot be assessed through vehicle deliveries alone.
Financing operations, cash flow and credit conditions also influence consolidated results.
Why This Matters for the Global Automotive Market
GM’s results show how carmakers are balancing competing demands.
Consumers want attractive vehicles at manageable prices.
Manufacturers need to fund expensive model launches and new technologies.
Investors expect profitability and cash returns.
At the same time, tariffs, commodity prices and global supply chains can increase costs beyond management’s direct control.
GM’s strong third-quarter performance demonstrates the value of established high-margin products.
But the negative share-price reaction reveals how sensitive investors are to changes in future profitability.
The company’s ability to navigate the next year may influence broader expectations for the U.S. automotive industry.
The Biggest Test Comes in 2027
General Motors enters the final quarter of 2026 with strong reported earnings, substantial automotive cash flow and a new $20-billion buyback authorization.
Its North American pickup business remains an important competitive strength.
But the automaker also faces rising materials costs, tariff exposure, a transition to redesigned trucks, EV investment adjustments and intensifying hybrid competition.
Its updated outlook indicates that management expects significant cash generation, but investors remain concerned about the path ahead.
Strong quarterly earnings are valuable, yet future profits will depend on vehicle demand, manufacturing efficiency and the company’s ability to control costs.
General Motors generated $50 billion in quarterly revenue and $3.3 billion in net income while announcing another $20 billion in potential shareholder buybacks. But the bigger question is whether its truck-driven profits can withstand roughly $2 billion in potential additional cost pressure in 2027—and whether Wall Street will regain confidence before those challenges begin to affect earnings.