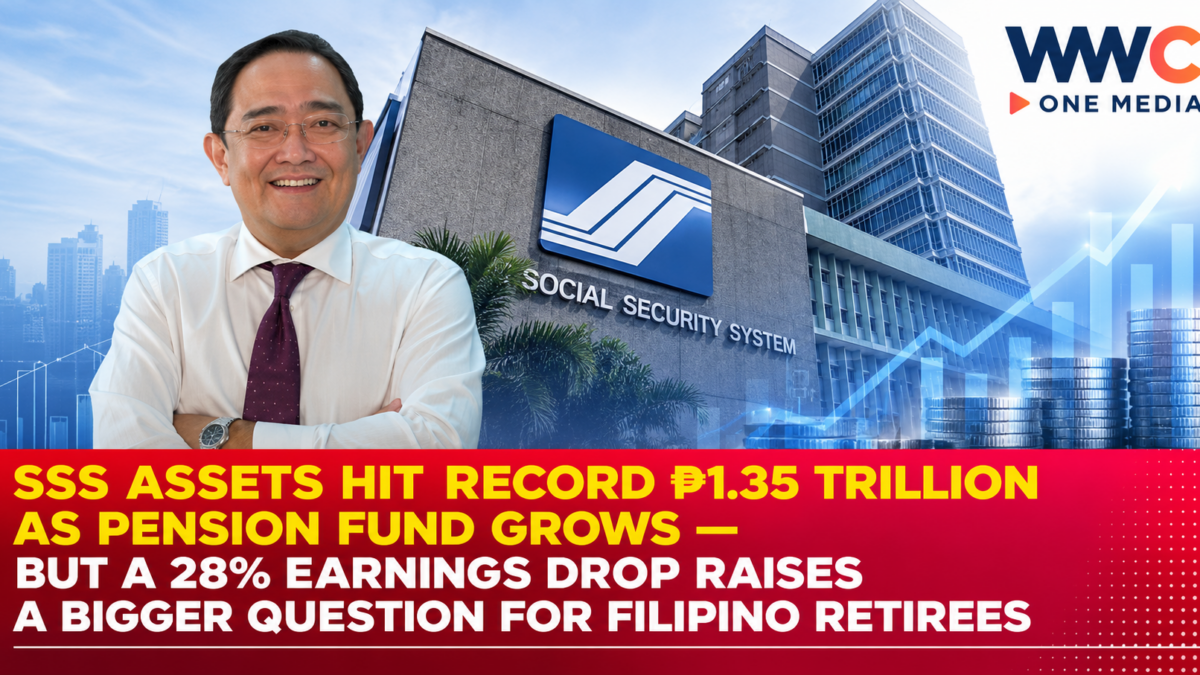
MANILA, Philippines — The Social Security System (SSS) has reached a historic financial milestone, with total assets climbing to a record ₱1.35 trillion as of June 2026, reinforcing the state pension fund’s resources for millions of Filipino workers, retirees and beneficiaries.
But behind the record-breaking figure is a more complicated financial picture.
While the government pension institution continues to accumulate investment reserves and collect higher member contributions, its benefit payments are growing faster than collections, and its first-half net income has declined sharply.
The figures raise an important question for Filipinos relying on SSS benefits:
Can the pension fund maintain its financial strength while paying higher pensions and preparing for the growing retirement needs of future generations?
SSS Assets Grow by Nearly ₱95 Billion in Six Months
According to an SSS announcement released in October, the institution’s total assets reached ₱1.35 trillion at the end of June 2026.
That represented an increase of ₱94.9 billion, or 7.6%, from the approximately ₱1.25 trillion reported in December 2025.
The growth reflects an expanding financial base supported by contributions, investment activity and other income-generating assets.
Its Investment Reserve Fund (IRF), which supports the payment of long-term pension and social security obligations, reached ₱1.31 trillion during the first half.
That was 6.6% higher than the ₱1.23 trillion recorded at the end of 2025.
The expansion comes as SSS prepares for a leadership transition following the departure of its president and chief executive officer, Robert Joseph Montes de Claro.
In its October 13 statement, SSS credited the administration’s investment management, risk controls and asset allocation practices with helping strengthen the institution’s financial position.
However, total assets should not be confused with money available for immediate distribution to pensioners.
The figure covers investments and other resources supporting both present and future obligations.
SSS Collects ₱200.32 Billion From Members and Employers
Contribution collections remained an important source of financial growth.
From January through June 2026, SSS collected ₱200.32 billion from members and employers.
That was 6.9% higher than the ₱187.44 billion collected during the comparable period in 2025.
The increase reflects stronger inflows supporting the pension and social insurance system.
Contributions help finance retirement pensions, disability benefits, death and survivor benefits, maternity benefits, sickness benefits and other eligible claims.
For employed members, the system depends on contributions from workers and their employers.
Self-employed, voluntary and other eligible members also contribute under applicable arrangements.
But the strength of contribution collections must be assessed alongside the growing amount that SSS is required to pay.
The central challenge is not simply collecting more money.
It is ensuring that contribution income and investment performance remain sufficient to support the institution’s obligations over time.
Pension and Benefit Payments Jump 19%
SSS disbursed ₱173.45 billion in benefits during the first six months of 2026, compared with ₱145.73 billion during the same period in 2025.
That represents a 19% increase in payments to pensioners and other qualified beneficiaries.
The increase is significant for households that depend on SSS payments to cover daily expenses, medicine, food, transportation and other necessities.
However, the rate of growth reveals an important financial imbalance.
Benefit payments increased 19%, while contribution collections rose only 6.9%.
In absolute terms, contributions still exceeded benefit payments by approximately ₱26.87 billion during the first half.
But the slower growth of contributions means SSS must continue generating sufficient investment income and managing its resources prudently.
The six-month difference between contributions and benefit payments is not a measure of the pension fund’s total profit or actuarial surplus.
Administrative expenses, investment results, other income and the institution’s long-term liabilities must also be considered.
Bigger Pension Payments Are Helping Millions of Filipinos
The increase in benefits comes as SSS implements its multiyear Pension Reform Program, which provides scheduled increases to eligible pensioners.
The program covers annual pension adjustments from 2025 through 2027.
Under the reform, retirement and disability pensioners receive annual increases of 10%, while death and survivor pensioners receive annual increases of 5%, subject to the applicable program rules.
The second tranche was implemented ahead of its original September 2026 schedule to help beneficiaries cope with higher living expenses.
In an October 15 statement, SSS reported that it had released ₱7.4 billion in additional pension benefits to approximately 4.1 million pensioners under the program.
For retirees, higher monthly benefits can provide financial relief amid increasing household costs.
For SSS, however, the additional payments also create greater recurring obligations.
The institution must therefore balance more generous benefits today with its responsibility to maintain adequate financial resources for future retirees.
But SSS Net Income Fell Nearly 28% in the First Half
While the latest announcement emphasizes record assets, earlier financial reporting identified a challenge that deserves equal attention.
According to an August 10 report by The Philippine Star, SSS net income declined 27.8% to approximately ₱48 billion during the first half of 2026.
That compares with ₱66.45 billion during the same period in 2025.
The decline occurred even as total income increased approximately 11% to ₱254.83 billion.
Expenses rose faster, climbing 26.8% to ₱206.8 billion.
The figures indicate that higher revenue was not enough to prevent an earnings decline as benefit payments and other expenses increased.
This does not mean SSS was operating at a loss.
The institution remained profitable during the first half.
It does, however, demonstrate why a record asset figure alone cannot provide a complete picture of its financial performance.
For pensioners and contributing workers, both asset growth and the sustainability of future benefit payments matter.
SSS Eyes ₱1.5 Trillion in Assets by December
Despite the drop in first-half earnings, SSS remains optimistic about its full-year financial performance.
The institution expects net income to exceed ₱100 billion by the end of 2026.
It also projects total assets of approximately ₱1.5 trillion by December.
Reaching that asset target would require an increase of about ₱150 billion from the reported June level.
These figures are management projections, not confirmed year-end results.
Actual performance will depend on contribution collections, benefit payments, investment returns, operating expenses and economic conditions during the remaining months.
The gap between first-half income and the full-year profit target also means SSS would need considerably stronger earnings in the second half to meet its projection.
That makes the final six months of 2026 important for assessing whether the institution can sustain both its asset growth and profitability.
Where Is the Trillion-Peso Pension Fund Invested?
SSS does not keep its entire reserve fund in bank deposits.
The institution invests across several asset classes to generate income and support long-term pension obligations.
According to an August 12 SSS announcement, consolidated investments reached ₱1.27 trillion at the end of June 2026.
The portfolio included:
- ₱629.05 billion in government securities.
- ₱179.44 billion in equities.
- ₱154.56 billion in property.
- ₱151.90 billion in member loans.
- ₱96.34 billion in corporate notes and bonds.
- Additional investments across other permitted asset classes.
Government securities accounted for the largest portion of the portfolio, reflecting the importance of relatively stable fixed-income investments.
Equities and other investments can offer opportunities for higher returns but are also exposed to financial market volatility.
Member loans represent another significant use of SSS investment resources.
The fund’s long-term performance depends on how effectively it manages these different sources of income and risk.
SSS Responds to Concerns About Stock Market Investments
The pension fund’s investment strategy has also attracted public scrutiny over stock market valuation losses.
In an October 15 statement, SSS defended its investment management practices and emphasized that its portfolio is diversified across different types of assets.
The agency explained that a paper loss occurs when an investment’s current market value falls below its acquisition value.
Such a decline does not automatically represent a realized loss from selling the investment.
However, unrealized losses remain economically relevant because they reflect changes in asset values and could become realized if securities are sold at lower prices.
SSS reported receiving approximately ₱9 billion annually in dividends from its equity investments.
According to BusinessMirror, the institution recorded ₱27.157 billion in investment income during the first half of 2026.
The same report said SSS was exploring additional investments in listed equities, real estate investment trusts and preferred shares.
These investments offer opportunities to generate returns but require effective risk management.
The Social Security Act of 2018 requires SSS to manage its reserve fund prudently and in accordance with its responsibilities to members and beneficiaries.
SSS Considers International Investments to Diversify Risk
Another important development concerns the fund’s investment strategy beyond the Philippines.
In August, SSS announced plans to explore additional foreign investment opportunities while continuing to support domestic financial markets.
Diversification into international assets could reduce reliance on the performance of the Philippine economy and local stock market.
It may also provide access to different industries, currencies and investment opportunities.
However, foreign investments introduce additional risks, including exchange-rate fluctuations, international market volatility and differences in regulatory environments.
For a pension institution, the objective is not simply to chase higher returns.
Investment decisions must support the ability to meet long-term benefit obligations while maintaining appropriate safeguards for members’ contributions.
What the ₱1.35-Trillion Milestone Means for SSS Members
For millions of Filipino workers and pensioners, the record asset figure is an encouraging indication that the institution’s financial resources have continued to grow.
A stronger investment reserve can help SSS absorb economic disruptions and meet benefit obligations.
But the amount of assets held by the institution does not determine an individual member’s retirement pension.
Actual benefits depend on applicable SSS rules, contribution records, credited years of service and eligibility requirements.
The latest announcement also does not establish a new across-the-board pension increase beyond the existing reform program.
Members should therefore distinguish between growth in SSS financial resources and specific changes to their own benefits.
The more important long-term issue is whether the fund can continue generating enough income to meet both current and future claims.
The Bigger Challenge: Can SSS Sustain Higher Benefits for Decades?
The Philippines faces the continuing challenge of protecting workers and retirees through a sustainable social security system.
SSS must support current pensioners while accumulating resources for contributors who may not retire for many years.
That requires prudent investments, dependable contribution collections, effective administration and realistic planning for future obligations.
The institution’s latest figures provide reasons for optimism.
Assets and reserves have reached record levels, while collections and investment resources have continued growing.
But the same figures also show why sustainability deserves attention.
Benefit payments are increasing faster than contributions, and net income declined sharply in the first half of the year.
Those developments do not establish that the pension fund is in immediate financial danger.
They do, however, underscore the importance of maintaining strong long-term financial management.
The Real Test for the Philippines’ Pension Fund
SSS has reached a historic milestone with ₱1.35 trillion in assets and ₱1.31 trillion in investment reserves.
The achievement strengthens the institution’s financial foundation and demonstrates continued growth in the resources supporting Filipino workers and pensioners.
Its latest projections suggest the fund could approach ₱1.5 trillion in assets by the end of the year.
But the true measure of success will not be the size of the balance sheet alone.
It will be whether SSS can maintain sustainable returns, finance higher pension payments and protect future generations of contributors.
The Social Security System has never reported a larger asset base. But with benefit payments rising faster than contributions and first-half earnings falling nearly 28%, the bigger question is whether record financial resources